EU E-Invoicing Is a Delivery Problem, Not Just Finance
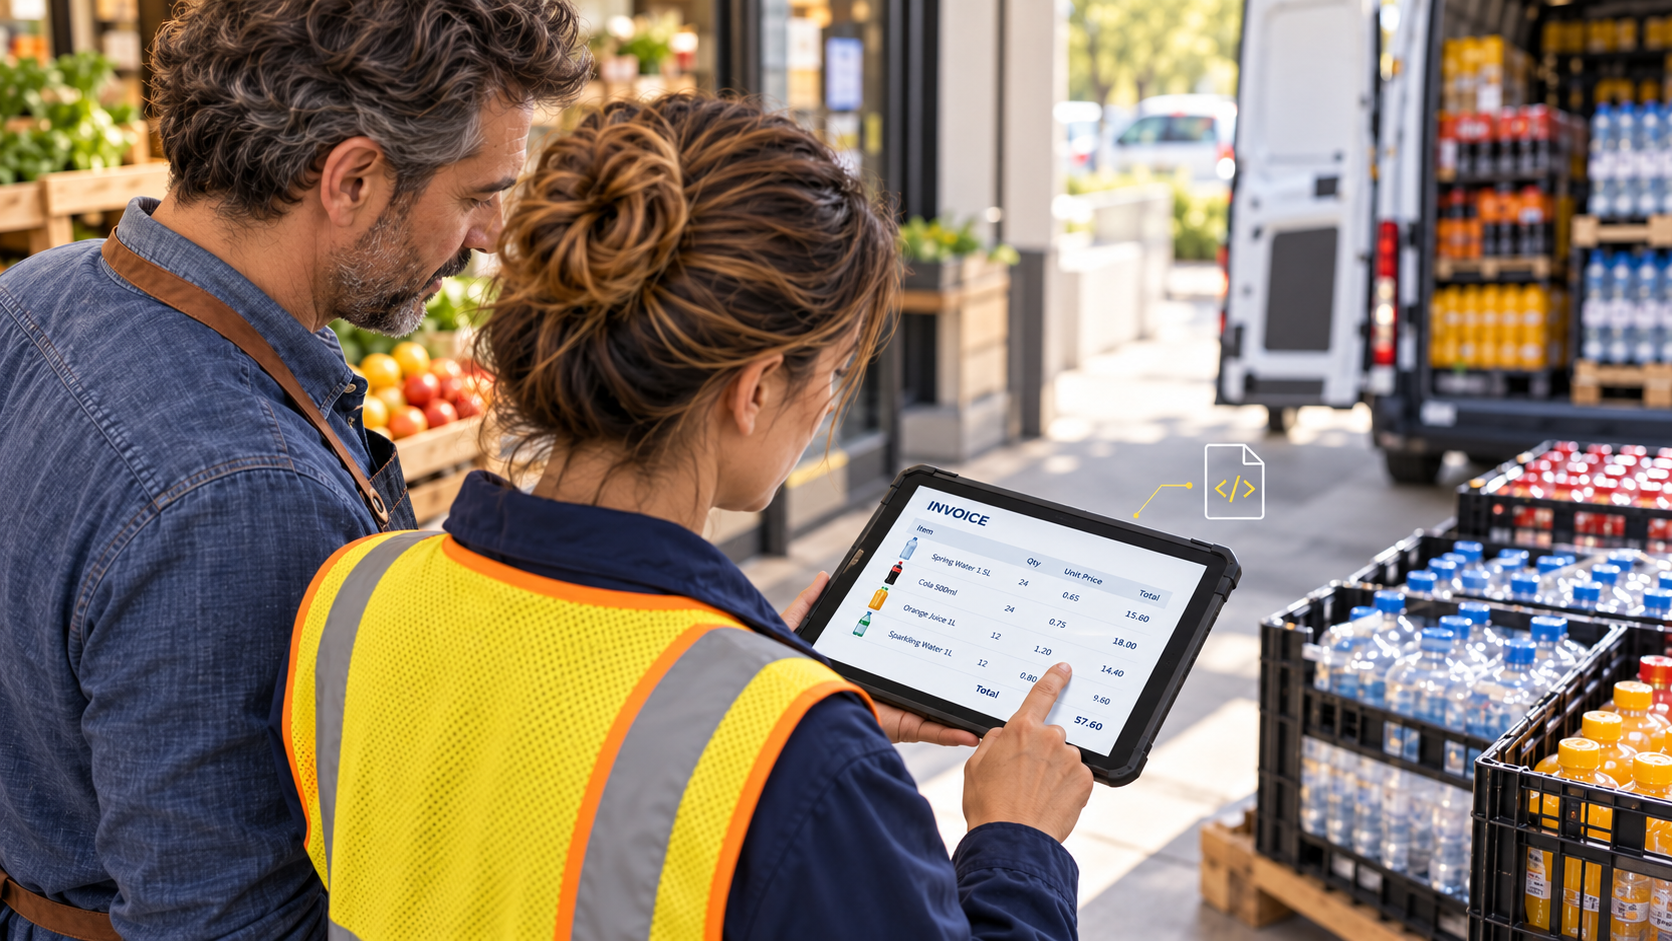
Most e-invoicing programmes are being run out of finance, and that is exactly why they will miss the hardest part. The invoice that matters in distribution is not the one generated in the back office at month-end. It is the one generated at the customer's door — on a van, on a route, on a tablet that may have had no signal five minutes earlier. If that document is not a valid structured e-invoice at the moment it is produced, no amount of ERP configuration downstream will fix it.
What the mandates actually require
Structured e-invoicing is not "emailing a PDF." It means the invoice exists as machine-readable data — XML in a named format — that the buyer's system reads and books without anyone retyping a field. In Europe that standard is EN 16931; in the Gulf it is ZATCA's UBL profile or the UAE's Peppol PINT AE. A PDF, however tidy, is a picture of an invoice.
The deadlines that matter for distribution teams are already arriving:
Market | Status (as of late 2026) | What it runs on |
|---|---|---|
Belgium | Domestic B2B live since 1 Jan 2026 | Peppol BIS Billing 3.0 over the Peppol network |
Poland | KSeF live for large taxpayers Feb 2026, all others Apr 2026 | National FA(3) schema via the KSeF platform |
France | Receiving from 1 Sep 2026; issuing phased by size through Sep 2027 | Factur-X / UBL / CII via approved platforms |
Germany | Receiving live since 1 Jan 2025; issuing from 1 Jan 2027 (larger) and 1 Jan 2028 (all) | XRechnung / ZUGFeRD on EN 16931 |
EU cross-border | Structured e-invoicing + digital reporting from 1 Jul 2030 (ViDA) | EN 16931 |
Saudi Arabia | Clearance waves reached most VAT registrants during 2026 | ZATCA FATOORA, UBL 2.1 |
UAE | Large businesses go live 1 Jan 2027; the rest 1 Jul 2027 | Peppol PINT AE, five-corner model |
Oman | 1 Apr 2027 (large), 1 Oct 2027 (others) | Peppol combined with OTA clearance |
Directive (EU) 2025/516 — the VAT in the Digital Age package, known as ViDA — is the reason this is accelerating. Since April 2025 member states can mandate domestic e-invoicing without asking the EU for permission, and from 1 July 2030 structured e-invoicing becomes the basis for cross-border intra-EU B2B reporting. The national systems are not being unified. They are multiplying: each with its own format, its own route, and its own definition of what counts as a valid invoice.
Why the point of delivery is the hard part
In most of the enterprise, the invoice is created after the fact: the order is picked, shipped, and invoiced in the ERP. In DSD, van sales, and direct distribution that sequence is reversed. The invoice is a legal document created at the visit — quantities negotiated on the spot, prices adjusted, substitutions agreed, the document signed or printed and handed to the customer.
And it has to reflect what actually landed, not what was ordered. Shorts, substitutions, refusals at the door, catch-weight adjustments and price overrides all change the invoice before it is issued. That is precisely why a finance-side e-invoicing project struggles: the data it needs most is born in the field, in an environment the finance system never sees.
Three things make the field document the hard case:
It must be structured at source. A re-typed summary produced the next morning is not the invoice that was issued; it is a reconstruction. Transcription is where fidelity dies — and fidelity is the whole point of the mandate.
It is generated in low or zero connectivity. Routes run through basements, rural roads, and dead zones. The document has to be created reliably offline and become transmittable when the device reconnects.
It is also the credit document. A refusal or a damaged crate in the same visit produces a credit note, which under the same rules must be structured too.
The re-keying trap
The common pattern is a chain: the driver prints or hand-writes an invoice in the field; it comes back to the office; someone re-keys it into the ERP; the ERP or an add-on produces a structured e-invoice; an access point or approved platform transmits it. Every link looks reasonable in isolation. Together they mean the structured document is produced from a second-hand account of the transaction, hours or days after it happened.
There is a compliance question here and there is an operational one. The compliance question is whether the transmitted document faithfully reflects the invoice the customer received. The operational question is the one distribution leaders already recognise: if the field event and the financial document are separate records, every later amendment is a manual reconciliation.
Where ERP integration stops being enough
Deep ERP integration is necessary and not sufficient. An ERP produces a perfectly valid structured e-invoice for any event it receives — the failure mode is not format generation, it is event fidelity. If the quantity was negotiated in the field and the ERP was told about it two days later by a human, the structured output is deterministic but the underlying data is not faithful.
Two honest constraints on our side. First, offline-first capture means the structured record is completed on the device and finalised when it syncs — that is what makes the field document reliable, but it does not make connectivity irrelevant. Second, Peppol transmission is a separate leg: Dynamics Mobile's job is to capture the delivery or van-sale event and generate the invoice and credit from that same record; exchange over Peppol, a clearance platform, or an approved platform is normally handled at the ERP or finance layer, or by an accredited access point. Know which leg is whose.
A five-point readiness checklist for operations teams
Find every place an invoice is created outside the ERP. Van sales, DSD routes, direct delivery, on-site adjustments, returns. If a document is handed to a customer in the field, it is in scope.
Check whether the delivery record and the invoice are one record. If a quantity change requires two edits in two systems, the structured invoice sits downstream of a manual step.
Confirm the field app works fully offline and syncs the financial event, not just the visit. A visit note that syncs but an invoice that must be re-keyed is still a paper process with extra steps.
Map credit notes and refusals to the same standard. Returns create credit documents; if they are issued by a different tool, they fall outside the mandate.
Decide who owns transmission. Capture, generation, and Peppol or clearance exchange are three different capabilities. Name an owner for each before a deadline names one for you.
What to do this year
You do not need to solve every country at once. Pick the market with the nearest live date and test one route end to end: negotiate an adjustment at the door, generate the structured invoice from that event with no re-keying, and transmit it. The gap you find will not be in the invoice format generator. It will be in the field. Fix it there, and the rest of the calendar becomes configuration rather than a project.
Related reading: Electronic Document Delivery: Close the Loop on Every Visit, Boost Van Sales: 6 Practical Workflow Simplifications with Mobile Invoicing, and DSD Digital Transformation: A GMS Checklist for Food Distribution.